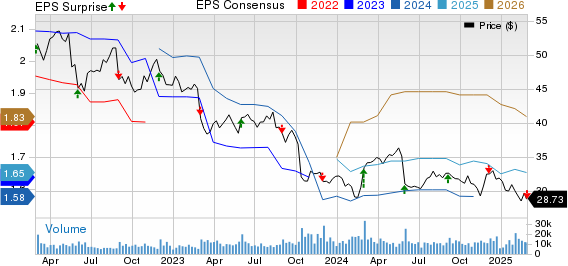
Hormel Foods Reports Q1 FY2025 Earnings Results Amid Declining Sales
Hormel Foods Corporation (HRL) released its first-quarter fiscal 2025 results, reporting declines in both net sales and earnings compared to the previous year. While the company’s earnings missed the Zacks Consensus Estimate, its net sales exceeded expectations. All segments experienced a decrease in volumes.
For the quarter, Hormel Foods reported adjusted earnings of 35 cents per share, down from 41 cents in the same quarter last year. This figure fell short of the Zacks Consensus Estimate, which was set at 37 cents.
Find the latest EPS estimates and surprises on Zacks Earnings Calendar.
Net sales for the quarter reached $2,988.8 million, a slight decline of 0.3% from $2,996.9 million in the previous year. Nevertheless, this figure surpassed the consensus estimate of $2,939.5 million. The overall volume decreased by 4.2% compared to the prior year.
Quarterly Results: Key Metrics and Insights
Hormel Foods’ gross profit for the quarter was $475.2 million, down from $508.7 million from the same period last year. Selling, general and administrative expenses rose to $263 million, compared to $240.4 million in the previous year.
Adjusted operating income declined to $254 million from $294.8 million, reflecting a decrease in adjusted operating margin to 8.5% from 9.8% reported a year earlier.
Revenue and Profit Insights by Segment
In the Retail segment, net sales fell by 1.1% year over year to $1,890.1 million, with volumes decreasing by 3.7%. The decline in sales of snack nuts, affected by production disruptions at their Suffolk facility, contributed to the downturn. However, key brands such as Applegate natural and organic meats, SPAM, Hormel Black Label bacon, Jennie-O, and Wholly guacamole saw growth.
Segment profit in Retail dropped by 20%, largely due to reduced sales and rising raw material costs in the Snacking & Entertaining category. Increased costs and unfavorable market conditions for whole turkey also played a role. Nevertheless, gains from the Transform and Modernize (T&M) initiative and margin growth in Emerging Brands and Convenient Meals & Proteins segments partially mitigated these challenges.
In the Foodservice segment, net sales grew by 1.9% to $930.2 million, despite a 4.7% drop in volume. The growth stemmed from a robust portfolio of solutions-based products and a strong direct-selling organization. Key products, including Hormel Fire Braised meats and Cure 81 ham, achieved volume and sales growth. Segment profit fell by 8% as margin pressures impacted results, even with increased sales.
In the International division, net sales decreased by 2.4% year over year to $168.5 million, with volumes plummeting 6.9%. Growth in China and increased exports of SPAM, Skippy peanut butter, and fresh pork were countered by weaker demand in Brazil, leading to lower commodity turkey exports. Segment profit improved by 4%, buoyed by higher export margins and growth in China, but this was hampered by poorer performance in Brazil.
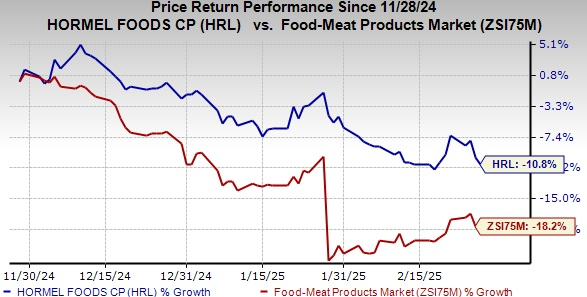
Image Source: Zacks Investment Research
Financial Health Snapshot
Hormel Foods, holding a Zacks Rank of #3 (Hold), concluded the quarter with cash and cash equivalents totaling $840.4 million and a total long-term debt of $2,850.2 million. Cash flow from operations was reported at $309.2 million.
The corporation is committed to returning capital to its shareholders, having returned nearly $155 million through dividends during the quarter.
Advancing Growth with T&M Initiative
Hormel Foods made strides in its T&M initiative, particularly with key advancements in the Move pillar, which includes preparations for a new distribution center in Memphis aimed at improving inventory flow and operational capacity. Additionally, the divestment of the last sow farm reinforces the company’s strategy to reduce commodity exposure and streamline operations. Hormel anticipates realizing $100 million to $150 million in further benefits from the T&M initiative in fiscal 2025.
Outlook for FY2025
Hormel Foods projects that fiscal 2025 net sales will range from $11.9 billion to $12.2 billion, forecasting organic net sales growth of 1% to 3%. Operating income expectations have been set between $1,118 million and $1,212 million, while adjusted operating income is anticipated to fall between $1,175 million and $1,275 million for the fiscal year. Previously, projections for operating income were between $1,129 million and $1,223 million.
The company’s annual earnings per share (EPS) are now estimated to be between $1.49 and $1.63, a decrease from earlier expectations of $1.51 to $1.65. The adjusted EPS guidance remains steady at between $1.58 and $1.72. Hormel Foods plans capital expenditures of $275 million to $300 million and expects depreciation and amortization expenses of approximately $265 million for fiscal 2025.
In the past three months, HRL’s stock has seen a decline of 10.8%, outperforming the industry, which has dropped 18.2% during the same timeframe.
Top Consumer Staple Picks
Pilgrim’s Pride (PPC) is a leading player in fresh, frozen, and value-added chicken and pork products, currently holding a Zacks Rank of 1 (Strong Buy). PPC has consistently delivered a positive earnings surprise of 25.7% on average over the trailing four quarters. You can view the complete list of today’s Zacks #1 Rank stocks here.
The current Zacks Consensus Estimate indicates a 5.4% decline in Pilgrim’s Pride’s earnings for the current financial year compared to last year’s reported results.
Tyson Foods, Inc. (TSN) operates globally as a significant food company.
Tyson and Post Holdings Show Promising Growth in Earnings
Currently, Tyson Foods Inc. (TSN) holds a Zacks Rank #2 (Buy). Over the trailing four quarters, TSN has posted an average earnings surprise of approximately 52%. The Zacks Consensus Estimate for Tyson Foods’ current fiscal-year sales and earnings suggests growth of nearly 0.9% and 22.6%, respectively, when compared to the figures from the previous year.
Post Holdings Inc. (POST), a consumer-packaged goods holding company, also carries a Zacks Rank of 2. Its trailing four-quarter average earnings surprise stands at 22.3%. The Zacks Consensus Estimate for Post Holdings indicates a growth forecast of 0.3% for sales and 2.2% for EPS relative to last year’s numbers.
Five Stocks with High Potential Returns
In an effort to spotlight promising investment opportunities, Zacks experts have identified five stocks as top picks expected to deliver returns of 100% or more in 2024. While not every pick will undoubtedly succeed, previous selections have achieved remarkable returns, soaring by +143.0%, +175.9%, +498.3%, and even +673.0%.
Many of the stocks featured in this report are not widely recognized on Wall Street, suggesting a unique chance for investors to seize potential gains early.
Discover These 5 Potential Home Run Stocks >>
Hormel Foods Corporation (HRL) : Free Stock Analysis Report
Tyson Foods, Inc. (TSN) : Free Stock Analysis Report
Pilgrim’s Pride Corporation (PPC) : Free Stock Analysis Report
Post Holdings, Inc. (POST) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
The views and opinions expressed herein are the views and opinions of the author and do not necessarily reflect those of Nasdaq, Inc.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.