Pinterest, Inc. (PINS) reported a 11% year-over-year increase in global monthly active users, reaching 640 million in the second quarter of 2026. This growth is attributed to stronger advertiser demand driven by the company’s AI-driven advertising platform, Pinterest Performance+, which automates aspects of campaign management and improves return on ad spend. Pinterest also launched new features like Smart Assembly and is developing an AI-based Business Assistant to enhance advertisers’ experiences.
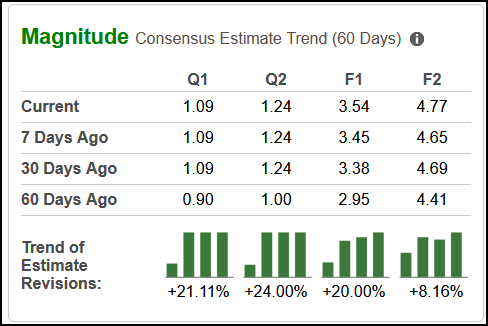
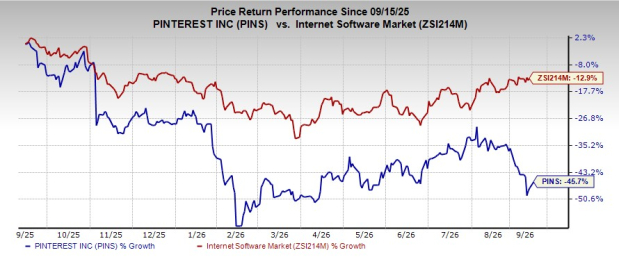
Despite these advancements, Pinterest’s stock has declined 45.7% over the past year, compared to a 12.9% decline in the industry. The company currently has a forward price-to-sales ratio of 2.06, below industry averages. The Zacks Consensus Estimate for Pinterest’s earnings has increased over the past 60 days, indicating potential for future growth.
In comparison, competitors such as Meta Platforms, Inc. (META) and Snap, Inc. (SNAP) are also leveraging AI in advertising, with Meta reporting a 28% increase in Family of Apps revenues to $60.4 billion in the second quarter of 2026.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.