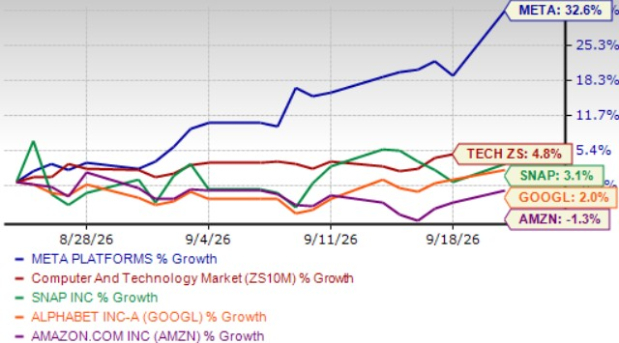
Meta Platforms, Inc. (META) shares have surged 32.6% over the past month, significantly outpacing the Zacks Computer & Technology sector’s 4.7% increase. Factors driving this rally include strong advertising fundamentals, enhanced confidence in Meta’s AI monetization strategy, the recent launch of Muse, and reduced regulatory uncertainty following a youth-safety settlement in August. However, capital expenditures for the second quarter of 2026 hit $31.08 billion, up from $17.01 billion a year prior, putting pressure on investor sentiment.
As of the second quarter of 2026, Meta reported over 3.6 billion daily users across its platforms including Facebook, Instagram, and WhatsApp, with Instagram alone reaching 2 billion daily active users. The company has seen nine million small businesses utilizing its AI advertising tools, reinforcing that its significant AI investments are yielding results. Despite this, Meta faces challenges with operating losses from its Reality Labs division and rising long-term debt, which increased to $83.66 billion as of June 30, 2026.
The Zacks Consensus Estimate for Meta’s third-quarter 2026 earnings is projected at $6.39 per share, a decline of 3.3% over the past month, while total revenue is expected to range between $61 billion and $64 billion. This reflects a potential 23.3% growth year-over-year, despite the financial strain posed by capital expenditures and competition from AI-driven platforms like Google’s Gemini and OpenAI’s ChatGPT.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.