Co-authored with “Hidden Opportunities”
“They don’t make them like they used to.” I often hear this about the purchased goods, equipment, vehicles, and houses from my grandparents and often from my parents. This expression is often used to convey a sense of nostalgia or admiration for the perceived durability, craftsmanship, or quality of products from the past compared to more contemporary ones. Today, I’m going to discuss this from a human capital perspective.
A study from 2016 revealed that 47% of high school students graduated with grades in the A range. And since then, grades have only gone up. It isn’t just the prices of goods and services that have soared since the pandemic; academic grades have also experienced the steepest inflation ever.
“The average high school GPA increased by 0.19 grade points, from 3.17 in 2010 to 3.36 in 2021, with the greatest grade inflation occurring between 2018 and 2021.” – ACT.org
Grade inflation, as they call it, is worsening and is most prominently seen in higher-income school districts. So, are American students really getting brighter? Sadly, no. Between 1998 and 2016, while the average high school G.P.A. rose, the average SAT scores fell from 1026 to 1002. Among students of the class of 2023, ACT scores were the worst in over three decades.
There’s no shortage of disapproval of the Generation Z population by older members of the workforce. Managers in several industries reveal that Gen Z employees are difficult employees lacking motivation or focus in the workplace. Moreover, Gen Z pursues frequent job-hopping, with the lowest average time spent in a role among all other generations (two years and three months).
Moreover, with remote work, there are increased occurrences of moonlighting (taking up multiple full-time jobs without properly disclosing it to employers and performing the bare minimum on each role) and quiet quitting, severely impacting the workforce’s productivity.
Complaints about the current “young” generation aren’t anything new. Fears for the future aren’t anything new. My parents and grandparents had a lot of negatives to say about my generation. I think we did alright, but I might be biased.
As the world changes, so too will those who take over the companies we invest in and rely on to fund our retirements. Perhaps the scariest thing for retirees to face is that their investments are in the hands of people they can’t control.
As investors, we are direct beneficiaries of stellar strategy through execution and a capable management team can make all the difference for our returns. When we buy a company, we know who is managing it. However, will those who manage our investments in the future be as excellent? We can’t guarantee that.
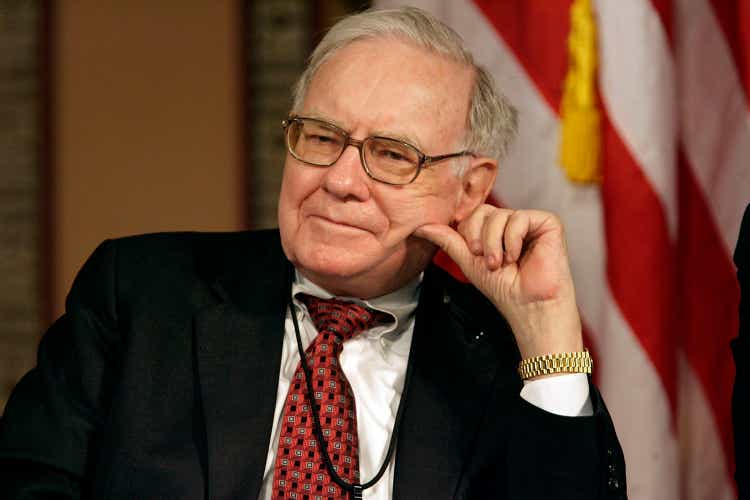
It’s that unknown that led Warren Buffett to famously state:
“I try to invest in businesses that are so wonderful that an idiot can run them. Because sooner or later, one will.” – Warren Buffett
Let us look at two picks from asset-heavy industries that provide critical services to the population with terrific pricing power to help “idiot-proof” our income and retirement. Let’s dive in!
Bolstering Reliability With UTF – Yield 8.8%
There are lingering doubts about the state of the economy – will we achieve a hard landing, a soft landing, or no landing at all? But no matter the outcome, we should invest in a manner that allows our income to thrive.
The U.S. continues down three notable paths
-
Low-carbon energy systems
-
Expand domestic manufacturing
-
Larger data centers for energy-intensive artificial intelligence needs
These initiatives have solid backing from the Federal government through three notable programs – the IIJA (Infrastructure Investment and Jobs Act), the IRA (Inflation Reduction Act), and the CHIPS (Creating Helpful Incentives to Produce Semiconductors) Act. Billions in federal and state government funding will flow into several companies’ top lines, ensuring robust profitability as high material costs fade.
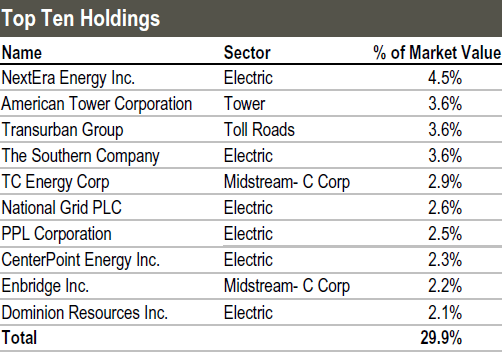
We like this defensive sector and seek to improve the reliability of our income through diversified exposure to this lucrative yet deeply discounted sector. Cohen & Steers Infrastructure Fund (UTF) is a highly diversified fund with its assets invested across 248 companies. The company’s top 10 positions are some of the largest electric utility, midstream, and roadway companies, constituting about ~30% of the asset value. The extensive diversification provides an excellent cushion for the fund to ensure distribution safety from the trio of federal programs. Source
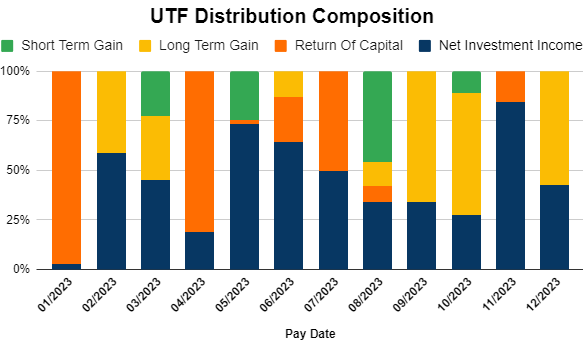
UTF operates with a 30% leverage, with 85% carrying a fixed weighted average interest rate of 1.8% and a duration of three years. The fund distributes $0.155/month, an 8.8% annualized yield, and this distribution is fueled through a combination of net investment income, capital gains, and some return of capital.
It must be noted that UTF reported almost $545 million in unrealized asset appreciation on its semi-annual report from June 20, 2023. This is adequate to fuel the shareholder distributions for more than three years.
As America continues to build a modern power grid with an increased mix of renewables and natural gas, bringing manufacturing jobs home, and improving our roadways and railways, you can collect your share from UTF’s monthly distributions. The CEF trades at a modest 2% discount to NAV, making it a bargain to lock in high yields from a defensive sector that’s well positioned to see substantial cash infusion in the years ahead.
Second Pick: Antero Midstream – Yield 7.4%
Global macros point to energy prices to remain volatile in 2024. But midstream’s defensive contracts, fee-based operating
The Resilient Rise of Antero Midstream Corporation
In the realm of energy stocks, Antero Midstream Corporation, or AM, reigns supreme as a champion of infrastructure for natural gas and LPG exports to international markets. The company serves as a vital link, delivering these critical energy sources to developing nations, where they are indispensable resources. Moreover, AM stands out for providing superior gathering and processing services to Antero Resources (AR), all under the guise of long-term fixed-fee service agreements.
A Greener Advantage
Not content with just leading the charge in energy exports, AM has also taken up the mantle of sustainability by orchestrating a closed-loop system of freshwater pipelines and storage facilities. This ingenious setup enables the company to deliver water directly to pad sites, significantly boosting operational efficiency and cost-effectiveness. Furthermore, this environmentally friendly method of water transportation far surpasses the carbon footprint left behind by traditional truck-based delivery systems.
Financial Fortitude
AM’s financial prowess is apparent, with the company attaining a remarkable milestone of generating a record $251 million in adjusted EBITDA during Q3, marking a robust 12% year-over-year growth. Notably, AM also managed to amass $30 million in free cash flow after dividends during the same period, signifying an enviable level of profitability and reinforcing its status as a robust contender in the energy sector.
Navigating the Fiscal Terrain
Looking ahead, AM’s management has outlined ambitious plans for the future, projecting adjusted EBITDA between $970-990 million for FY 2023, alongside a forecast of $565-585 million in free cash flow. These figures, coupled with the quarterly dividend payout of $0.23 per share, which yields an impressive 7.3% annually, reinforce the company’s commitment to delivering substantial returns to its investors.
Debt Defiance
AM’s proactive stance on debt management is equally commendable, with the company successfully extinguishing $106 million in debt year-to-date, effectively lowering the net leverage to 3.4x from 3.7x at the end of FY 2022. This concerted effort to reduce debt not only bolsters the company’s financial standing but also augurs well for mitigating interest expenses in the face of burgeoning borrowing costs across industries.
The Road Ahead
Undoubtedly, AM’s strategic maneuvering and robust financial performance serve as a harbinger of success in an environment rife with uncertainty. As the U.S. grapples with escalating demands for natural gas exports and the associated need for expanded infrastructure, AM’s unwavering asset utilization and burgeoning free cash flow render it a formidable force in the energy sector, posing as an enticing prospect for income-seeking investors.
The Unwavering Pursuit of Stability
In today’s dynamic investment landscape, the quest for unwavering stability and resilience is paramount. AM’s enduring commitment to financial prudence and sustainability, coupled with its robust position in the energy market, renders it a beacon of hope for investors seeking reliable income sources. As the future unfolds, the saga of Antero Midstream Corporation promises to be a tale of steadfast resilience and unwavering prosperity in the face of an ever-evolving financial landscape.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.