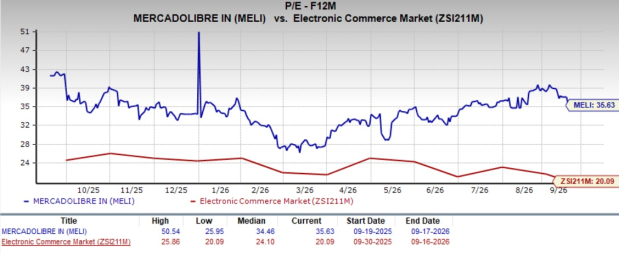
MercadoLibre, Inc. (MELI) is currently trading at a forward price-to-earnings (P/E) multiple of 35.63, significantly higher than the industry average of 20.09 and its one-year median of 34.46. The premium valuation comes amidst profitability challenges, with the company reporting a second-quarter operating margin of 6.7%, down 550 basis points year-over-year due to increased investments and higher logistical expenses, particularly in Brazil.
Over the past year, MELI stock has declined by 26.3%, underperforming both the retail industry and the S&P 500, which gained 14.8% in the same period. While the company reported its first quarterly revenues over $10 billion, earnings per share estimates have been lowered from $41.00 to $39.11 for the current fiscal year, indicating increasing caution among analysts.
Management faces additional challenges in Mexico due to tax reform and a weaker economic environment, further pressuring margins. Despite the robust growth in e-commerce and fintech segments, continuing negative earnings estimate revisions make it difficult to justify the stock’s current premium valuation.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.