Reliance, Inc.’s RS stock looks promising at the moment. It is gaining from demand strength in its major end-use markets, a diversified product base and strategic acquisitions.
We are positive on the company’s prospects and believe that the time is right for you to add the stock to portfolio as it looks promising and is poised to carry the momentum ahead.
Let’s delve deeper into the factors that make this Zacks Rank #1 (Strong Buy) stock an attractive choice for investors right now.
An Outperformer
RS has outperformed the industry it belongs to over a year. The company’s shares have rallied 20.9% compared with a 12.4% rise recorded by the industry.
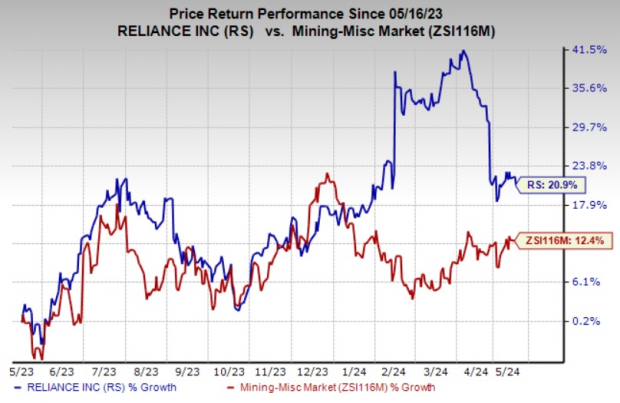
Image Source: Zacks Investment Research
Earnings Estimates Northbound
Over the past two months, the Zacks Consensus Estimate for Reliance for 2024 has increased around 1.7%. The consensus estimate for second-quarter 2024 has also been revised 5.6% upward over the same time frame. The favorable estimate revisions instill investor confidence in the stock.
Superior Return on Equity (ROE)
Reliance’s ROE of 16.3%, as compared with the industry average of 3.6%, manifests the company’s efficiency in utilizing shareholders’ funds.
Strong Demand, Acquisitions Aid RS
Reliance is benefiting from strong underlying demand in its major markets. In the first quarter, Reliance saw an uptick in demand for non-residential construction, particularly in sectors like public infrastructure, manufacturing and energy infrastructure. The momentum is expected to continue into the second quarter of 2024, with an anticipated ongoing strength in these sectors.
The commercial aerospace demand also remained relatively stable, a trend that Reliance predicts will continue in the second quarter, with some variability depending on supply chain factors and production rates. Military and space-related aerospace demand is expected to remain consistently strong during the same period.
Moreover, the semiconductor market showed a seasonal improvement after a flat fourth quarter of 2023. Reliance holds a positive long-term outlook for the semiconductor industry, buoyed by the CHIPS Act and major U.S. semiconductor fabrication projects.
RS has been following an aggressive acquisition strategy for a while as part of its core business policy to drive operating results. The acquisitions of Rotax Metals, Admiral Metals and Nu-Tech Precision Metals are in sync with its strategy of investing in high-quality businesses.
The acquisition of Southern Steel Supply also expands the company’s reach in the Southern United States and boosts its value-added processing services. The buyout of Cooksey Iron & Metal Co also boosts Reliance’s presence in the fast-growing Southeastern market. Moreover, the acquisition of American Alloy will expand Reliance’s product portfolio with specialty carbon steel plates as well as new production capabilities.
Reliance projects a stronger-than-usual seasonal recovery in demand for the second quarter of 2024 despite ongoing macroeconomic and geopolitical uncertainties. The company expects its tons sold to increase by 2.5-4.5% from first-quarter 2024 levels, with about 2% of this growth coming from new acquisitions completed on Apr 1, 2024.
Reliance, Inc. Price and Consensus

Reliance, Inc. price-consensus-chart | Reliance, Inc. Quote
Other Stocks to Consider
Other top-ranked stocks worth considering in the basic materials space include ATI Inc. ATI, Carpenter Technology Corporation CRS and Ecolab Inc. ECL.
ATI carries a Zacks Rank #1. ATI beat the Zacks Consensus Estimate in each of the last four quarters, with the average earnings surprise being 8.3%. The company’s shares have soared around 73% in the past year. You can see the complete list of today’s Zacks #1 Rank stocks here.
Carpenter Technology currently carries a Zacks Rank #1. CRS beat the Zacks Consensus Estimate in three of the last four quarters while matching it once, with the average earnings surprise being 15.1%. The company’s shares have soared roughly 131% in the past year.
The Zacks Consensus Estimate for Ecolab’s current-year earnings is pegged at $6.59 per share, indicating a year-over-year rise of 26.5%. ECL, a Zacks Rank #2 (Buy) stock, beat the consensus estimate in each of the last four quarters, with the average earnings surprise being 1.3%. The company’s shares have rallied roughly 34% in the past year.
Zacks Names #1 Semiconductor Stock
It’s only 1/9,000th the size of NVIDIA which skyrocketed more than +800% since we recommended it. NVIDIA is still strong, but our new top chip stock has much more room to boom.
With strong earnings growth and an expanding customer base, it’s positioned to feed the rampant demand for Artificial Intelligence, Machine Learning, and Internet of Things. Global semiconductor manufacturing is projected to explode from $452 billion in 2021 to $803 billion by 2028.
See This Stock Now for Free >>
Ecolab Inc. (ECL) : Free Stock Analysis Report
ATI Inc. (ATI) : Free Stock Analysis Report
Reliance, Inc. (RS) : Free Stock Analysis Report
Carpenter Technology Corporation (CRS) : Free Stock Analysis Report
To read this article on Zacks.com click here.
The views and opinions expressed herein are the views and opinions of the author and do not necessarily reflect those of Nasdaq, Inc.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.