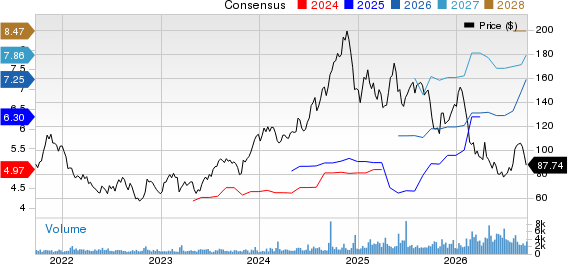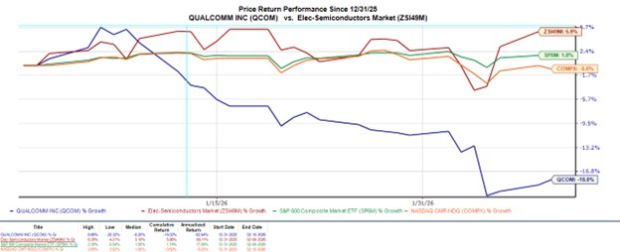
Qualcomm’s shares fell 5% following its fiscal first quarter report last Wednesday and are down nearly 20% year-to-date. Despite reporting record Q1 sales, the company’s revenue and EPS guidance for Q2 fell below Wall Street expectations, primarily due to a global memory chip shortage impacting smartphone demand. Qualcomm’s Q2 revenue guidance is set at $10.2–$11 billion, missing the consensus estimate of $11.1 billion, while EPS guidance of $2.45–$2.65 is below the anticipated $2.85.
The ongoing memory chip shortage has led original equipment manufacturers (OEMs) to reduce orders, further affecting Qualcomm’s core handset processor business. Over the past month, Qualcomm’s EPS estimates for fiscal years 2026 and 2027 have declined by over 7%, contributing to a Zacks Rank #5 (Strong Sell). The increasing demand for AI data centers has also diverted memory supplies from smartphones, exacerbating production delays for OEMs.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.