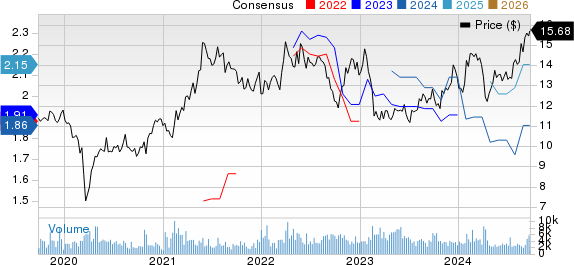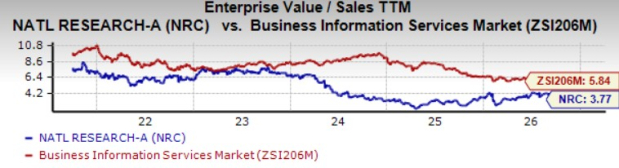
NRC Health currently trades at a trailing 12-month enterprise value/sales (EV/sales) multiple of 3.77X, approximately 35% lower than the industry average of 5.84X. Compared to its competitors, Experian plc and Iron Mountain Incorporated, which trade at 4.28X and 6.62X respectively, NRC’s valuation appears attractive. In the past year, NRC’s shares surged 53.3%, outperforming the industry’s 14.9% decline, while Experian’s shares dropped 30.3% and Iron Mountain’s increased by 11%.
NRC Health reported revenue of $66.1 million for the first half of 2026, up from $62.3 million a year prior, attributed to a strong subscription-based model. The total recurring contract value also increased, with remaining contract revenue of $188.3 million as of June 30, 2026. However, the company faced challenges including high SG&A expenses, increased long-term debt, and a $12.2 million working-capital deficit.
Currently, NRC is investing in technology and innovation, including AI capabilities, to enhance its offerings. Management anticipates improved margins as revenue growth increases and costs normalize, with adjusted EBITDA margins at 27% for Q2 2026. Although there are operational headwinds, NRC’s growth prospects and favorable valuation may present an investment opportunity.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.