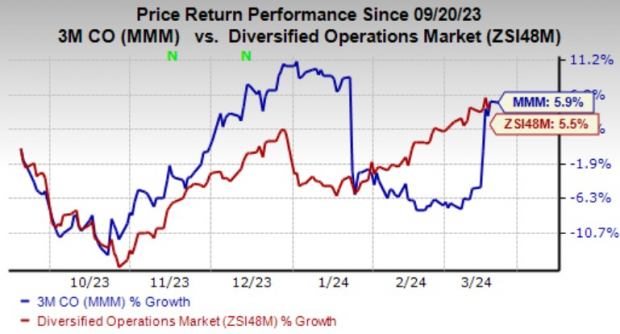
Driving Forces Behind 3M’s Success
3M Company (MMM) is riding the wave of success with its advanced materials, commercial solutions, and auto OEM businesses making significant strides. The company’s Transportation and Electronics segment has seen remarkable growth, driven by the surge in global car and light truck bills, leading to a 4.5% revenue boost in the fourth quarter of 2023.
On the financial front, 3M has upped the ante by revising its earnings guidance for the first quarter of 2024, with adjusted earnings expected to reach $2.05-$2.20 per share. This reflects a substantial 5.3% growth at the midpoint compared to the previous year.
Furthermore, 3M’s strategic acquisitions, like the technology assets of LeanTec and M*Modal’s technology business, have bolstered its market presence and revenue streams. In fact, in the fourth quarter of 2023, acquisitions contributed to a 0.2% increase in the company’s top line.
Challenges on the Horizon
Despite its remarkable performance, 3M has faced challenges in certain segments. The decline in sales within the Consumer segment due to softness in home health, auto, and stationery & office businesses warrants attention. Additionally, reduced demand for disposable respirators has negatively impacted the Safety and Industrial segment, leading to a sales dip of 2.7% in the last quarter of 2023.
Moreover, the company’s escalating debt levels, highlighted by long-term debt reaching $13.1 billion at the end of 2023, might pose risks to its financial stability and profitability. High interest expenses and financial charges further compound these concerns.
Promising Alternatives to Explore
For investors seeking diversification, there are alternative opportunities worth exploring within the industry:
Griffon Corporation (GFF), boasting a Zacks Rank #1 (Strong Buy), has shown robust performance with a 42% average earnings surprise in the trailing four quarters. Meanwhile, the Zacks Consensus Estimate for GFF’s fiscal 2024 earnings has experienced a 3.9% increase in the past 60 days.
Carlisle Companies Incorporated (CSL) presents another promising avenue with a Zacks Rank #1. CSL delivers an average earnings surprise of 7.6% in the trailing four quarters and has witnessed an 8.2% increase in the Zacks Consensus Estimate for its 2024 earnings over the past 60 days.
Vector Group Ltd (VGR) rounds up the list of viable options with a Zacks Rank #1. VGR’s performance is underscored by a 10.2% average earnings surprise in the trailing four quarters and a 6.9% improvement in the consensus estimate for its 2024 earnings in the previous 60 days.
Amidst the changing landscape, exploring these alternatives could provide a well-rounded investment strategy.
Unleash Your Portfolio’s Potential
As the financial markets continue to evolve, seizing opportunities like those offered by 3M (MMM) becomes paramount. Stay informed, stay engaged. The investment world holds a myriad of possibilities – it’s up to you to navigate them wisely.
To read more insights from Zacks Investment Research, click here.
Founded on diligent research and market insights, Zacks Investment Research strives to equip investors with the tools and knowledge needed to make informed decisions. Explore more.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.