Super Micro Computer, Inc (NASDAQ:SMCI), affectionately known as “SMCI”, recently experienced a revenue surge akin to what Nvidia famously witnessed, with its shares skyrocketing by 35% after significantly raising its quarterly guidance. This surge was propelled by SMCI’s dominant position in the AI hardware segment, propelling sales and profitability to exceed expectations. With SMCI’s earnings due to be revealed on January 30, the company’s stellar pre-announcement indicates that the results are poised to surpass previous projections.
SMCI’s recent outperformance suggests that analysts may need to raise future estimates to match the company’s extraordinary growth. Furthermore, the current valuation of SMCI remains relatively inexpensive. As a leading hardware supplier for the AI segment, SMCI is expected to continue bolstering sales and increasing profitability, leading to a higher stock price in the years to come.
Increased Confidence in SMCI
Having flagged SMCI recently, I had a hunch about its potential for outperforming expectations this quarter.
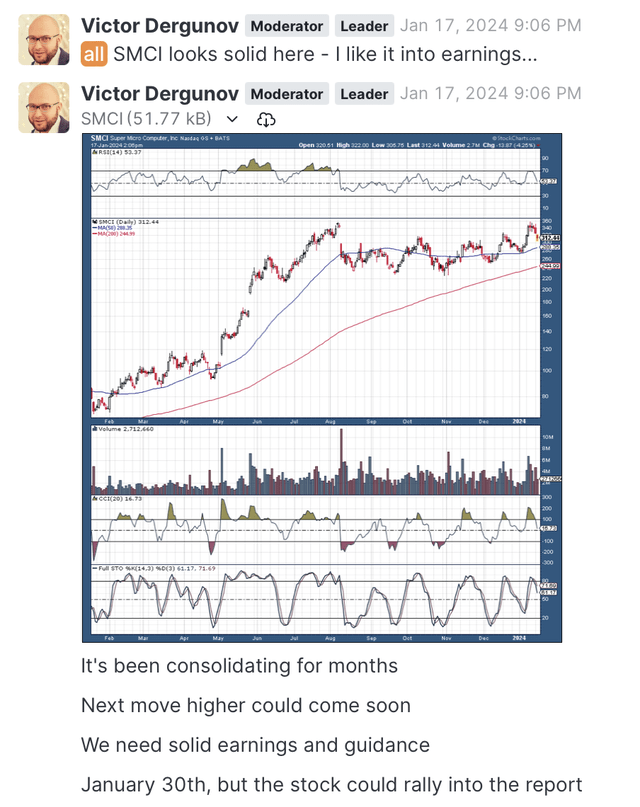
Subsequently, I augmented my SMCI position by 50%, and within a day, the stock surged by 35% during its “Nvidia moment”. I capitalized on this surge by selling covered call options against 33% of my stake and may consider further options if the price continues its upward spiral. Despite the likelihood of a near-term pullback/consolidation, my long-term bullish outlook on SMCI remains unwavering.
Technical Breakout to New Highs
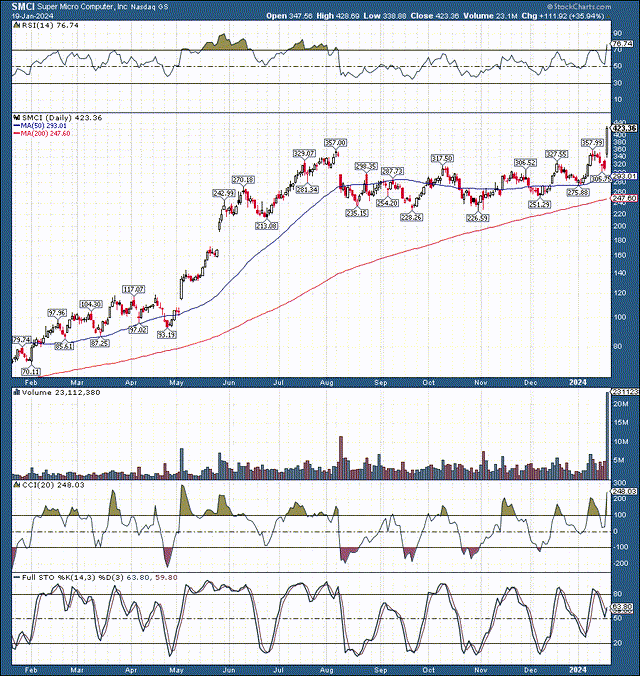
Technically, SMCI’s prolonged consolidation period, coupled with its relatively low valuation in comparison to its growth and profitability prospects, set the stage for the recent surge. Additionally, around 9% of SMCI’s shares were sold prior to its Nvidia moment, indicating that short-covering likely amplified the rapid price escalation. Considering the record volume and the RSI approaching 80, a phase of consolidation or pullback could ensue post-earnings. Nonetheless, SMCI remains a prime “buy the dip” opportunity in the coming months.
Riding the AI Boom
The ongoing AI boom has led to Super Micro’s impressive expansion in both top and bottom lines, surpassing expectations. SMCI anticipates fiscal Q2 revenues of $3.6-$3.65 billion, significantly higher than the previously projected $2.7-$2.9 billion range. This bullish momentum underscores an estimated revenue about 32% higher than consensus forecasts.
Furthermore, the updated EPS guidance is about $5.50, markedly surpassing the previous range of $4.40 to $4.88. The heightened guidance far exceeds the consensus estimate figures, depicting robust market and end customer demands for SMCI’s rack-scale, AI, and total IT solutions.
SMCI – Surpassing Sales Expectations
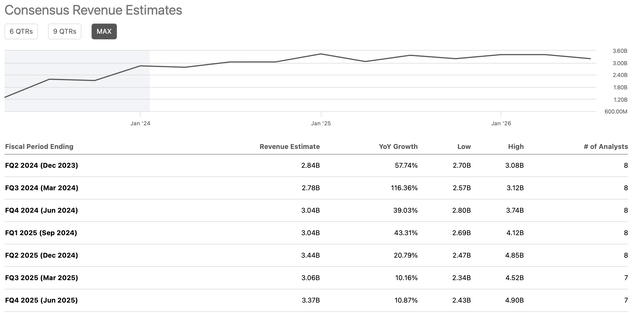
SMCI’s sales are projected to surpass expectations by approximately 32%, indicating that future estimates are unduly conservative. The previous fiscal Q2 revenue range of $2.7-$3.08 billion has been superseded by SMCI’s announcement of $3.6-$3.65 billion. Such robust outperformance necessitates a revision of future revenue estimates to accurately reflect the stellar sales growth potential of Super Micro.
Super Micro – A Deceptively Great Value
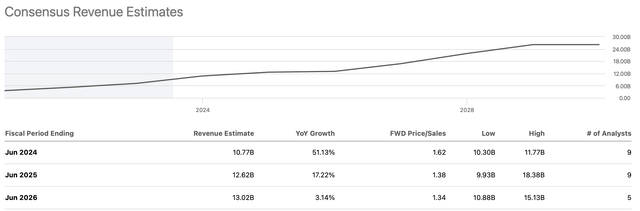
The revenue estimates for fiscal 2024 of $10.3 to $11.77 billion may well be eclipsed given the substantial surge in revenue guidance, potentially leading to sales in the region of $13-$14 billion if the company’s outperformance persists in subsequent quarters. This could result in considerably higher-than-expected revenues in the coming years, emphasizing that Super Micro’s current valuation is remarkably appealing. Hence, SMCI’s forward P/S multiple could be in the 1-1.2 range instead of the previously assumed 1.5-1.6 range.
Projected Profit Expansion
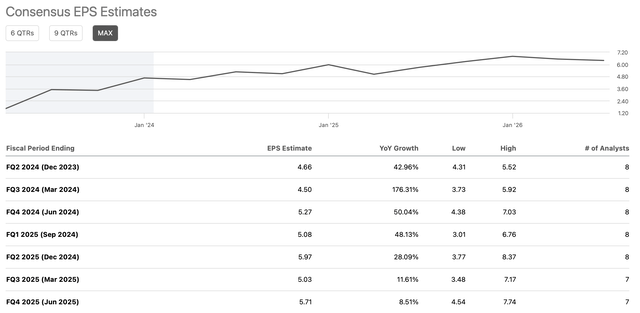
SMCI’s updated EPS guidance of $5.40-$5.55 for fiscal Q2 implies the potential to achieve figures at the higher end or beyond. Furthermore, future quarters may also see SMCI reaching or exceeding these upper-tier estimates, signifying that its EPS might outstrip earlier expectations. Should SMCI continue at this pace, it could earn around $20-$22 in EPS by fiscal 2024.
Underestimating SMCI’s EPS
Super Micro’s Opportunity and Risks Analysis
Projected Growth and Forward Valuation
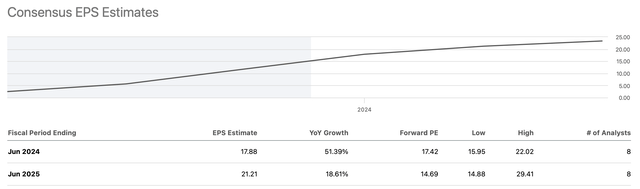
Super Micro Computer, Inc. (SMCI) is positioned to roar into its future like a well-oiled machine. With analysts predicting an earnings per share (EPS) of $17.88, SMCI is primed to exceed expectations by achieving around $21. This potential indicates that SMCI’s forward price-to-earnings (P/E) ratio for fiscal 2024 may rest at approximately 21.4, showcasing a potential undervaluation.
Looking ahead to 2025, SMCI’s EPS could soar even higher than the estimated $21.21 consensus. The company may be on a trajectory to reach an impressive $27-$29 in EPS for fiscal 2025. This outlook spells a modest 16-times forward (fiscal 2025) earnings for SMCI, an extraordinary value proposition for a market leader with promising growth prospects.
Future Potential
Projections for SMCI’s future paint an exhilarating picture. Revenue is envisioned to surge, reaching $21.7 billion in 2026. This represents a robust 22% growth from the previous year. Additionally, EPS is expected to climb to $34 during the same period, reflecting a 21% increase. As a result, the forward P/E is forecasted to be a modest 20, signaling continued attractive valuations for investors.
Where Super Micro’s stock could be in the future
Year after year, the numbers for SMCI paint a compelling story. Revenue is projected to witness an 85% surge in 2024, climbing to $13 billion. This growth trajectory is anticipated to continue, with revenue reaching $34 billion by 2030. Similarly, EPS is estimated to spiral to $58 by 2030, reflecting a 12% annual growth.
Risks to Super Micro
However, amid these prospects lurk potential challenges. SMCI faces the lurking specter of competition, as it vies against formidable adversaries in its industry. Moreover, the company may encounter margin pressures, given the intense rivalry in the AI hardware space. Macro factors such as a global economic slowdown could also cast a shadow over its growth trajectory. Furthermore, concerns persist regarding whether SMCI’s growth may plateau, leading to a stagnation or even a decline in EPS after its AI prowess peaks. These risks underscore the need for investors to conduct a thorough evaluation before considering a stake in SMCI.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.