“`html
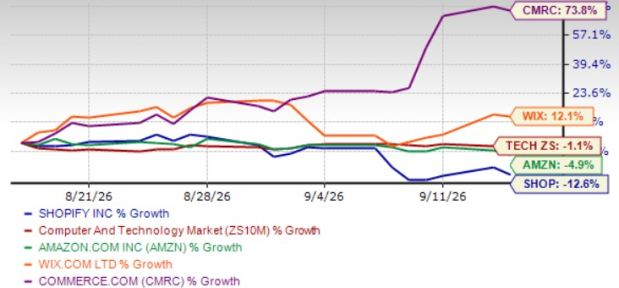
Shopify Inc. (SHOP) shares have dropped 12.6% in the past month, compared to a 1.1% decline in the broader Zacks Computer and Technology sector. The company reported second-quarter 2026 revenues of $3.58 billion, marking a 34% year-over-year increase, although third-quarter 2026 revenue growth is anticipated to slow to the low-30% range. Gross Merchandise Volume (GMV) rose to $115.6 billion, yet gross profit growth is expected to be in the mid-to-high-20% range.
Shopify’s Merchant Solutions segment is outperforming its Subscription Solutions, with a 37% revenue increase versus 22% for subscriptions. Notably, Shopify Payments accounted for 68% of GMV in Q2, up from 64% the previous year. However, Shopify faces competition from companies like Amazon, Wix.com, and Commerce.com, with their respective share price performances showing significant variations.
The Zacks Consensus Estimate for Shopify’s third-quarter earnings stands at 44 cents per share, indicating a year-over-year growth of 29.41%. Despite strong long-term prospects highlighted by AI-driven commerce and expanding merchant services, the company is viewed as overvalued with a forward price/sales ratio of 9.4X, significantly higher than the sector average of 5.98X.
“`
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.