Qualcomm Incorporated (QCOM) reported a decline in its QCT EBT margin to 26% from 30% year-over-year in the third quarter of fiscal 2026, and expects it to further decrease to 23-25% in the fourth quarter. The company attributes this margin pressure to rising semiconductor costs and weakening smartphone demand, with QCT handset revenues down 20% year-over-year to $5.09 billion.
As semiconductor costs rise; including wafer fabrication and advanced packaging, Qualcomm plans to implement price hikes, but existing fixed-price contracts will delay the impact. The company anticipates a 50% sequential decline in Apple-related revenue, lowering its forecasted modem share for iPhone launches from 20%.
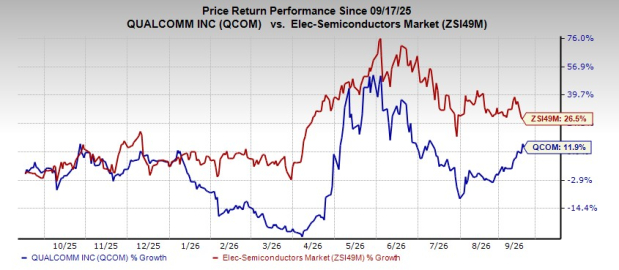
In comparison, competitors Intel Corporation and Advanced Micro Devices are reporting operating income increases, with Intel achieving $2.77 billion and AMD’s operating income rising by 245% to $3.09 billion in their latest quarters. Qualcomm’s stock has grown 11.9% over the past year, trailing the industry’s 26.5% growth, and currently has a Zacks Rank of #5 (Strong Sell).
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.